

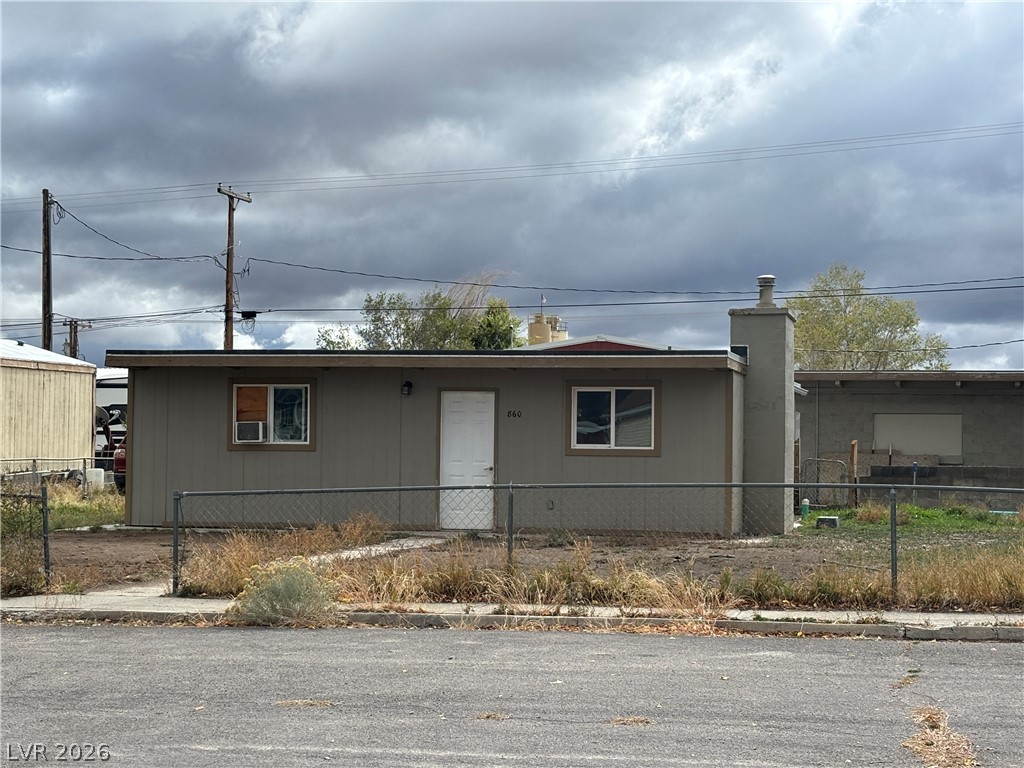
VA
Active
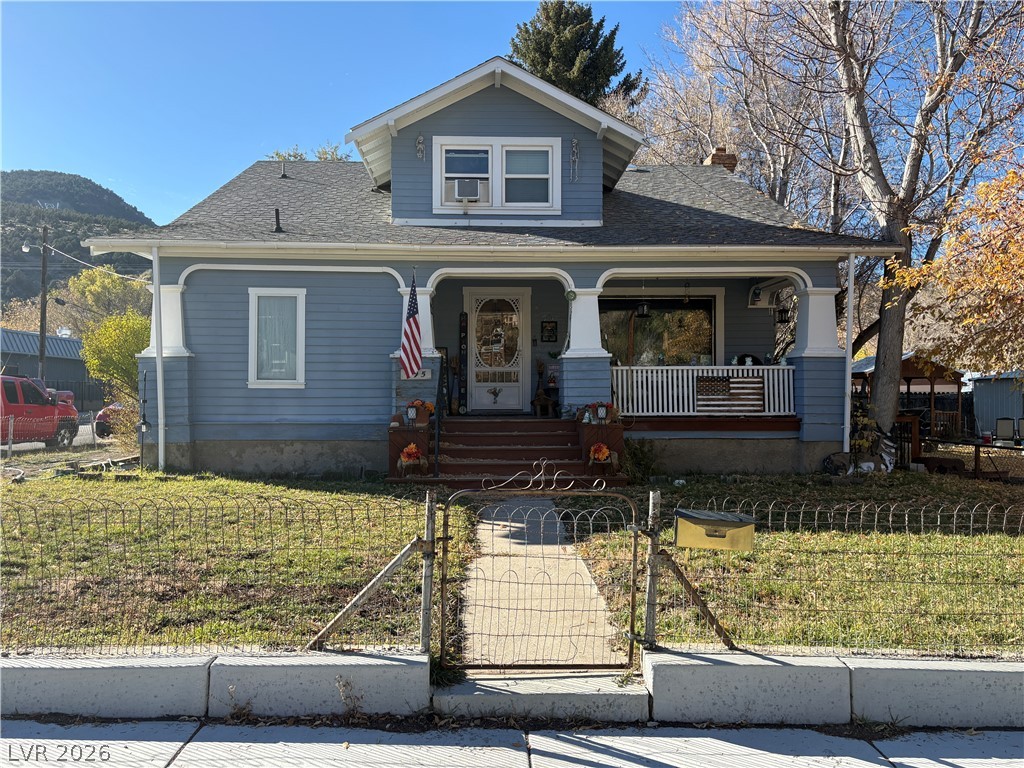
18$189,000$65,208 equity gap
- Rate
- 3.13%
7.18%today- Payment
- $601/mo
$949today
- 2beds
- 1baths
- 900sqft
McGill, Nevada
1 home in McGill carries an existing FHA, VA, or USDA loan you can take over, with locked rates from 6.06%. Assume the seller’s mortgage instead of financing at today’s 7.2%.
Live MLS data · Updated
McGill assumable market
by the numbers.
Every number on this page comes from the live MLS feeds UMe indexes for Nevada, filtered to McGill. Updated November 2026.
How assumptions work for buyersMcGill, Nevada has 1 home for sale with an assumable mortgage as of November 2026: 1 VA loan that a qualified buyer can take over at the seller's existing rate instead of financing at today's roughly 7.2%. Rates on active McGill assumable listings start at 6.06% with a median of 6.06%; 0 listings are under 4% and 0 are under 5%.
The median assumable home in McGill lists for $175,000, with a median of $24,204 in cash to assume, the gap between the price and the remaining loan balance. At the median assumable rate the principal-and-interest payment is about $916 a month versus $1,064 for the same balance at today's rate, roughly $148 kept every month and $1,771 a year. The most active McGill ZIP codes are 89318 (1).
UMe confirms the balance, rate, and assumability of each listing with the listing agent before marking it Certified. FHA, VA, and USDA loans are assumable by law, and you do not need to be a veteran to assume a VA loan. Once you are under contract, the loan servicer underwrites you rather than a new lender; most McGill assumptions close in 45 to 90 days, and UMe tracks the file with the servicer and both agents so nothing stalls.
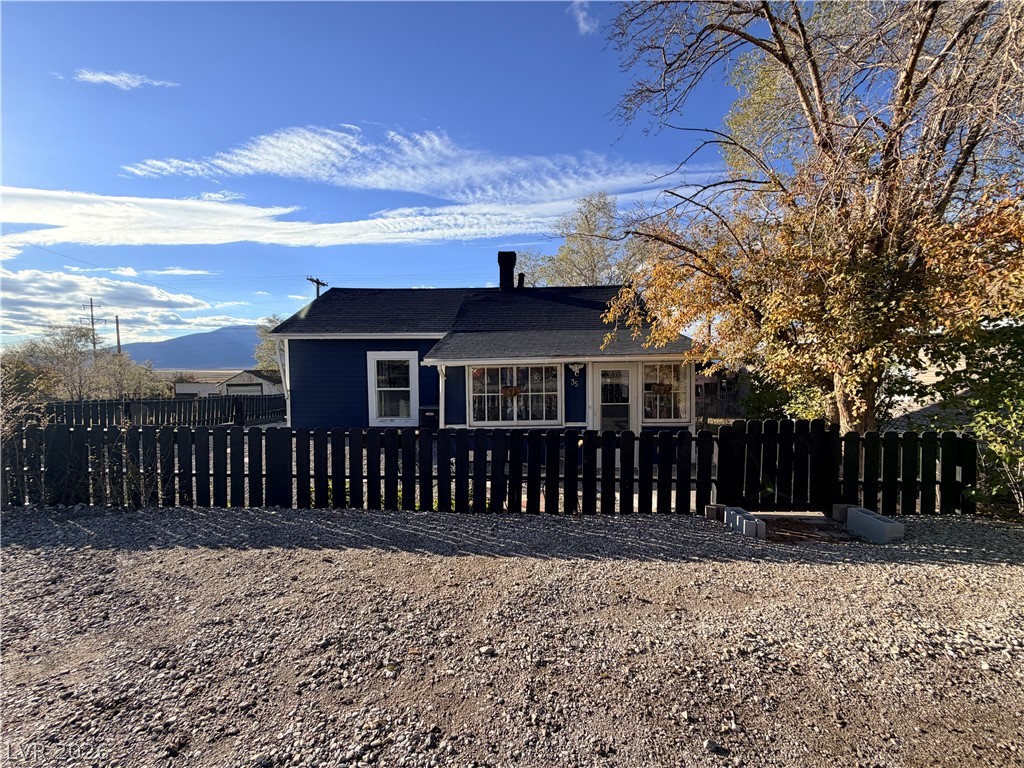
Live MLS collection. Loan balances, payment estimates, and cash-to-assume amounts update with the source listing. Taxes, insurance, HOA, closing costs, and secondary financing may change the final monthly payment.
Live counts from the MLS feeds we index for Nevada. Updated November 2026.
FHA, VA, and USDA loans are assumable by law. Conventional loans almost never are.
Each ZIP opens the McGill map zoomed to its listings, in assumptions mode, with rate and payment filters ready.
The sliders start at the median McGill assumable listing: $175,000 list price and a 6.06% existing rate. We compare the payment you would take over against financing the same balance with a new loan at today’s 7.20%. Principal and interest only; taxes, insurance, and HOA dues are the same either way.
The gap between price and balance is the seller’s equity: your cash to assume, or what a second loan can help cover.
14% of the price. Eligible buyers can start with as little as 5% down using a second loan for the rest.
Estimates for illustration. The real numbers depend on the loan, the servicer, and your qualification; every McGill listing on UMe shows the actual balance, rate, and payment.
You’re not applying for a new mortgage. You’re stepping into one that already exists, at the rate it was written. Four steps, and UMe owns the hard one.
Start with pre-qualificationEvery listing on this page carries an existing FHA, VA, or USDA loan. Filter the McGill map by existing rate, monthly payment, or cash to assume instead of by list price alone.
You pay the seller the difference between the price and the remaining balance, a median of $24,204 in McGill today. Cash, a second loan, or seller financing can bridge it.
The current loan servicer reviews your credit, income, and debt just like a lender would. UMe prepares the file, works the servicer directly, and chases every follow-up so the 45-to-90-day timeline holds.
The seller’s balance, rate, and remaining term become yours. No points, no origination fee, no reset to 30 years, and a McGill payment written in a different decade.
The numbers below come from current McGill inventory and update as listings change.
All assumption FAQsAs of November 2026, UMe tracks 1 active assumable listing in McGill. Inventory refreshes from the MLS throughout the day, so the map may show slightly different counts.
Current McGill inventory breaks down as VA (1, median 6.06%). FHA, VA, and USDA mortgages are assumable by law, which is why they make up nearly all assumable listings. Conventional loans usually carry a due-on-sale clause and cannot be assumed. You do not need to be a veteran to assume a VA loan, though the seller's entitlement stays tied up unless you substitute your own.
The lowest rate on an active McGill assumable listing is 6.06%, and the median across all 1 listing is 6.06%. 0 listings are under 4% and 0 are under 5%, compared with roughly 7.2% for a new 30-year loan today.
Across current McGill listings, the median principal-and-interest payment on the assumable loan is $916 per month versus $1,064 for the same balance at today's rates, a difference of about $148 every month, or $1,771 a year. The savings compound because you also keep the seller's remaining term instead of restarting a 30-year clock.
When you assume a loan you pay the seller the difference between the list price and the remaining loan balance. In McGill that gap is currently a median of $24,204 on a median list price of $175,000. Buyers cover it with cash, a second mortgage, or seller financing; UMe can connect you with lenders who write gap loans behind an assumption.
The McGill ZIP codes with the most active assumable listings are 89318 (1). Use the map to draw your own boundary or filter by rate, payment, and down payment inside any of them.
Most FHA and VA assumptions close in 45 to 90 days. The loan servicer, not a new lender, underwrites you, and servicer turnaround is the main variable. UMe tracks the file with the servicer and the listing agent so nothing stalls, and every listing shows whether the assumption has already been confirmed with the seller's side.
Every listing on the McGill map has a rate you can take over. Start with the ones in McGill, get pre-qualified in minutes, and let UMe carry the assumption to closing.
© Listing Service, All rights reserved. The data relating to real estate for sale on this website comes in part from the Listing Service. Real estate listings held by brokerage firms other than Wardley Real Estate are marked with the Listing Service logo and detailed information about them includes the name of the listing brokers. All information deemed reliable but not guaranteed and should be independently verified. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) nor Listing Service shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless.

Wardley Real Estate © is committed to and abides by the Fair Housing Act of Equal Opportunity.